
2026 Valid CIMAPRA19-F03-1 Real Exam Questions, practice CIMA Strategic level
Latest Success Metrics For Actual CIMAPRA19-F03-1 Exam (Updated 435 Questions)
NEW QUESTION # 40
Company ABC's management has noticed that Company BCD has quickly built up a 20% stake by buying shares in Company ABC and are concerned that this is the start of a hostile bid.
This build-up of shares triggers the poison pill provision which automatically converts the rights to buy future preference shares previously issued to existing shareholders in Company ABC to full ordinary shares
What is the most likely impact of the triggering of a poison pill strategy at this stage in the bidding process?
- A. It is too late for a poison pill strategy to have any impact on a hostile takeover because Company BCD has already built up a significant stake in Company ABC.
- B. Company ABC becomes less attractive due to a fall in value of the shares as a result of the discount.
- C. The threat of a hostile takeover is reduced because Company ABC becomes more expensive to buy.
- D. Company BCD loses value on its shareholding and has to sell at a loss before losing more value
Answer: C
NEW QUESTION # 41
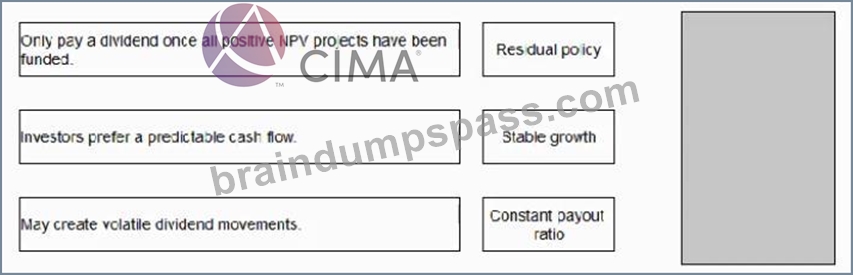
Select the most appropriate divided for each of the following statements: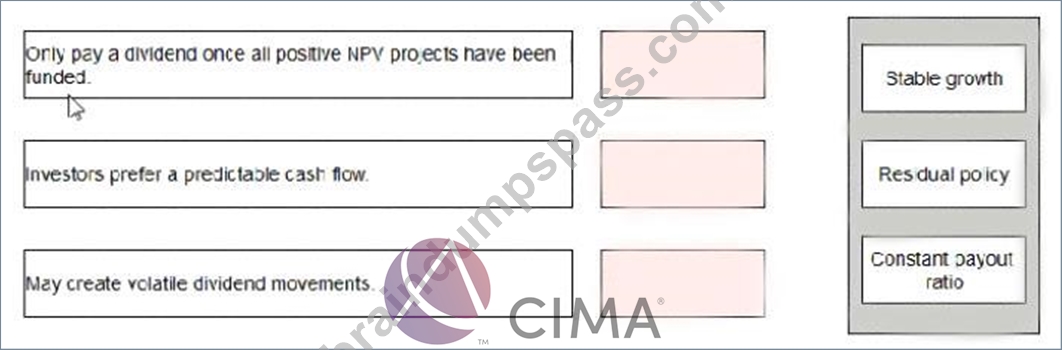
Answer:
Explanation: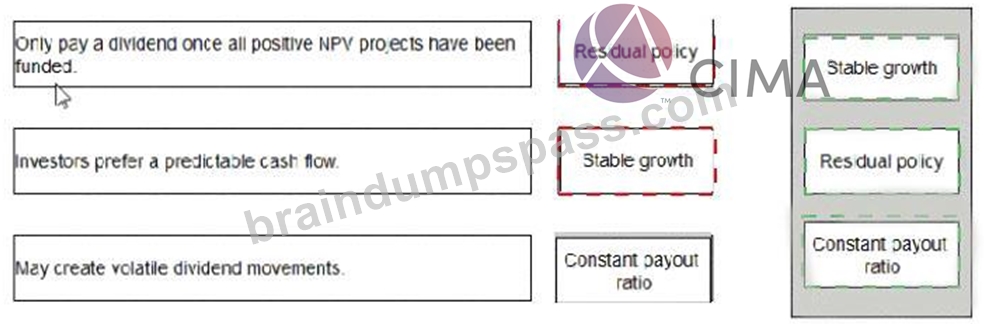
NEW QUESTION # 42
A company is planning a share buyback. In which of the following circumstances would a share buyback be appropriate?
- A. The company wants to reduce its gearing.
- B. The company has a one off cash surplus and no available investment opportunities.
- C. The country in which the company operates taxes capital gains at a higher rate than income.
- D. The company wants to reduce the nominal value of its shares to make them more marketable.
Answer: B
NEW QUESTION # 43
TTT pic is a listed company. The following information is relevant: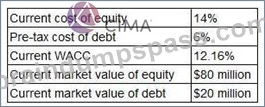
TTT pic's board is considering issuing new 6% irredeemable debt to re-purchase equity. This is expected to change TTT pic's debt to equity mix to 40: 60 by market value. The corporate tax rate is 20%.
What will be TTT pic's WACC following this change in capital structure?
- A. 12.67%
- B. 11.66%
- C. 11.09%
- D. 13.43%
Answer: C
NEW QUESTION # 44
Company AAB is located in country A whose currency is the AS It has a subsidiary, BBA, located m country B that has the BS as its currency AAB has asked BBA to pay BS40 million surplus funds to AAB to assist with a planned new capital investment in country A The exchange rate today is AS1 = BS3 Tax regimes
* Company BBA pays withholding tax of 25% on all cash remitted to the parent company
* Company AAB pays tax of 10% on at cash received from its subsidiary
How much will company AAB have available for investment after receiving the surplus funds from BBA?
- A. A$ 12 million
- B. A$ 9 million
- C. A$ 27 million
- D. A$ 81 million
Answer: B
Explanation:
Workings:
BBA remits BS40 million.
Withholding tax in country B = 25%:
Tax = 25% × 40 = BS10m
Net remitted = 40 # 10 = BS30m
Company AAB pays tax of 10% on cash received:
Tax = 10% × 30 = BS3m
Net after tax = 30 # 3 = BS27m
Exchange rate: A$1 = BS3 #
\text{AAB receives in A$} = \frac{BS27m}{3} = \text{A\$9m}
NEW QUESTION # 45
A listed company is financed by debt and equity.
If it increases the proportion of debt in its capital structure it would be in danger of breaching a debt covenant imposed by one of its lenders.
The following data is relevant: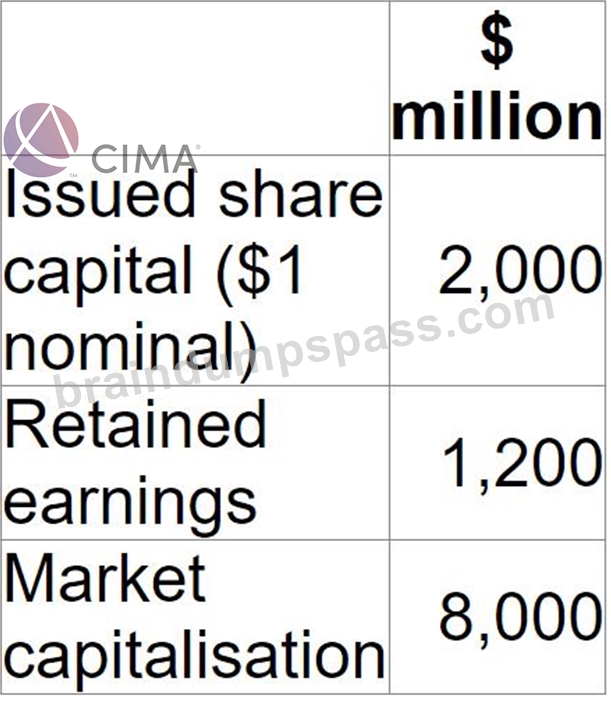
The company now requires $800 million additional funding for a major expansion programme.
Which of the following is the most appropriate as a source of finance for this expansion programme?
- A. Retained earnings
- B. Rights issue
- C. Bank overdraft
- D. Private placement of a bond
Answer: B
NEW QUESTION # 46
Company C has received an unwelcome takeover bid from Company P.
Company P is approximately twice the size of Company C based on market capitalisation.
Although the two companies have some common business interests, the main aim of the bid is diversification for Company P.
The offer from Company P is a share exchange of 2 shares in Company P for 3 shares in Company C.
There is a cash alternative of $5.50 for each Company C share.
Company C has substantial cash balances which the directors were planning to use to fund an acquisition.
These plans have not been announced to the market.
The following share price information is relevant. All prices are in $.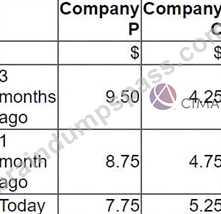
Which of the following would be the most appropriate action by Company C's directors following receipt of this hostile bid?
- A. Pay a one-off special dividend.
- B. Write to shareholders explaining fully why the company's share price is under valued.
- C. Change the Articles of Association to increase the percentage of shareholder votes required to approve a takeover.
- D. Refer the bid to the country's competition authorities.
Answer: B
NEW QUESTION # 47
Company A plans to acquire a minority stake in Company B.
The last available share price for Company B was $0.60.
Relevant data about Company B is as follows:
* A dividend per share of $0.08 has just been paid
* Dividend growth is expected to be 2%
* Earnings growth is expected to be 4%
* The cost of equity is 15%
* The weighted average cost of capital is 13%
Using the dividend growth model, what would be the expected change in share price?
- A. $0.03 increase
- B. $0.07 fall
- C. $0.16 increase
- D. $0.14 increase
Answer: A
Explanation:
Dividend Growth Model (DGM):
P0=D1ke#gP_0 = \frac{D_1}{k_e - g}P0=ke#gD1
Dividend just paid: D0=0.08D_0 = 0.08D0=0.08
Dividend growth: g=2%=0.02g = 2\% = 0.02g=2%=0.02
Cost of equity: ke=15%=0.15k_e = 15\% = 0.15ke=15%=0.15
Future dividend:
D1=D0(1+g)=0.08×1.02=0.0816D_1 = D_0 (1+g) = 0.08 \times 1.02 = 0.0816D1=D0(1+g)=0.08×1.02=0.
0816
Theoretical price:
P0=0.08160.15#0.02=0.08160.13#0.63P_0 = \frac{0.0816}{0.15 - 0.02} = \frac{0.0816}{0.13} \approx 0.63 P0=0.15#0.020.0816=0.130.0816#0.63 Current market price = 0.60 Expected change: 0.63#0.60=0.030.63 - 0.60 = 0.030.63#0.60=0.03 increase # Option A.
NEW QUESTION # 48
A national airline has made an offer to acquire a smaller airline in the same country.
Which of the following would be of most concern to the competition authorities?
- A. The acquisition is likely to result in significant redundancies of staff currently working for the smaller airline.
- B. After the acquisition the board propose to increase prices significantly on routes where no other airlines operate.
- C. After the acquisition the board propose to reduce the number of flight destinations from the country.
- D. The board informed a major institutional shareholder about the proposed acquisition before informing other shareholders.
Answer: B
NEW QUESTION # 49
Company A is planning to acquire Company B by means of a cash offer. The directors of Company B are prepared to recommend acceptance if a bid price can be agreed. Estimates of the net present value (NPV) of future cash flows for the two companies and the combined group post acquisition have been prepared by Company A's accountant. There are as follows: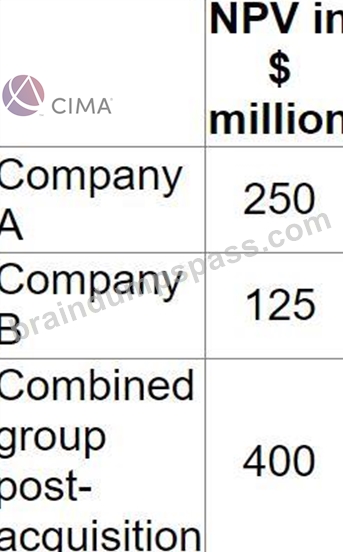
What is the maximum price that Company A should offer for the shares in Company B?
Give your answer to the nearest $ million
Answer:
Explanation:
150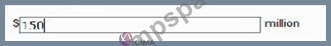
NEW QUESTION # 50
Company P is a large unlisted food-processing company.
Its current profit before interest and taxation is $4 million, which it expects to be maintainable in the future.
It has a $10 million long-term loan on which it pays interest of 10%.
Corporate tax is paid at the rate of 20%.
The following information on P/E multiples is available: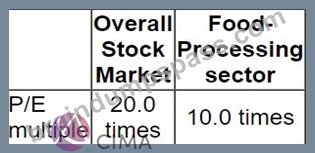
Which of the following is the best indication of the equity value of Company P?
- A. $40 million
- B. $24 million
- C. $80 million
- D. $48 million
Answer: B
NEW QUESTION # 51
Company A is located in Country A, where the currency is the A$.
It is listed on the local stock market which was set up 10 years ago.
It plans a takeover of Company B, which is located in Country B where the currency is the B$, and where the stock market has been operating for over 100 years.
Company A is considering how to finance the acquisition, and how the shareholders of Company B might respond to a share exchange or cash (paid in B$).
Which of the following is likely to explain why the shareholders of Company B would prefer a share exchange as opposed to a cash offer?
- A. It would enable them to benefit from the future performance of the combined entity.
- B. It would avoid them being exposed to foreign currency risk.
- C. It would allow them to realise their investment and make a capital gain.
- D. They would receive shares in a market that is likely to be more efficient.
Answer: A
Explanation:
Reasoning:
A share exchange allows Company B's shareholders to stay invested and participate in the future gains (synergies, growth) of the combined business.
A is wrong: cash offers are what "realise" an investment and crystallise a capital gain.
B is wrong: a share exchange introduces foreign currency exposure (to A$), whereas a cash offer in B$ does not.
C is wrong: Company B is in the older, more established market, so it is more likely that market is efficient, not Company A's.
So D is the correct explanation.
NEW QUESTION # 52
Company GDD plans to acquire Company HGG, an unlisted company which has been in business for 3 years.
Company HGG has incurred losses in its first 3 years but is expected to become highly profitable in the near future There are no listed companies in the country operating in the same business field as Company HGG The future success of Company HGG's business and hence the future growth rate in earnings and dividends is difficult to determine Company GDD is assessing the validity of using the dividend growth method to value Company HGG Which THREE of the following are weaknesses of using the dividend growth model to value an unlisted company such as Company HGG?
- A. The future projected dividend stream is used as the basis for the valuation
- B. The cost of capital will be difficult to estimate
- C. The dividend growth model does not take the time value of money into consideration
- D. The future growth rate in earnings and dividends will be difficult to accurately determine
- E. The company has been unprofitable to date and hence, there is no established dividend payment pattern
Answer: A,B,E
NEW QUESTION # 53
A company based in the USA has a substantial fixed rate borrowing at an interest rate of 3.5% and wishes to swap a part of this to a floating rate to take advantage of reducing interest rates Its bank has quoted swap rates of 3 4%-3 5% against 12-month USD risk-free rate.
What is the overall interest rate achieved by the company under this borrowing plus swap combination?
- A. 12-month USD risk-free rate
- B. 12-month USD risk-free rate plus 0.1% (where 0.1% = the fixed rate of 3.5% minus the swap rate of 3.4%)
- C. Unchanged at 3.60% as this is the same as the swap rate
- D. 12-month USD risk-free rate minus 0.1% (where 0.1% = the fixed rate of 3.6% minus the swap rate of 3.4%)
Answer: B
NEW QUESTION # 54
A company wishes to raise new finance using a rights issue to invest in a new project offering an IRR of
10%
The following data applies:
* There are currently 1 million shares in issue at a current market value of $4 each.
* The terms of the rights issue will be $3.50 for 1 new share for 5 existing shares.
* The company's WACC is currently 8%.
What is the yield-adjusted theoretical ex-rights price (TERP)?
Give your answer to 2 decimal places.
$ ?
Answer:
Explanation:
4.06, 4.060
NEW QUESTION # 55
Select the category of risk for each of the descriptions below: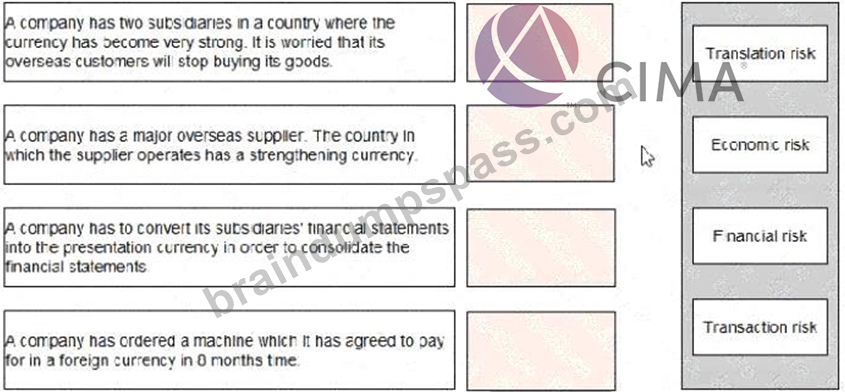
Answer:
Explanation: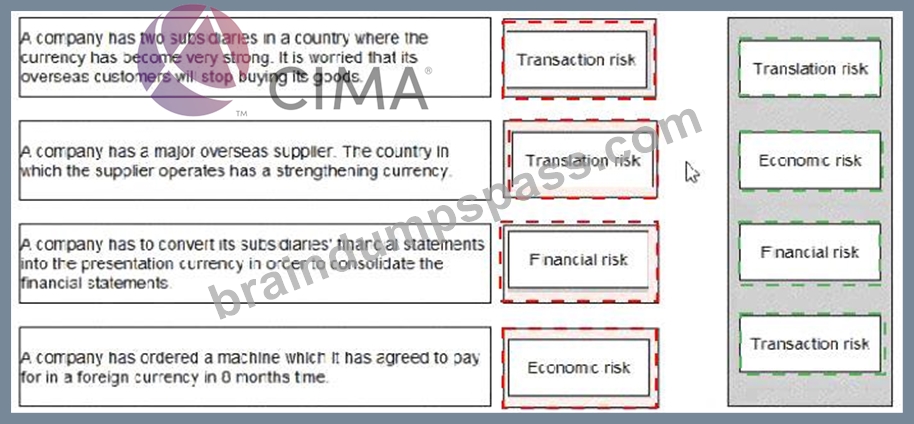
Explanation: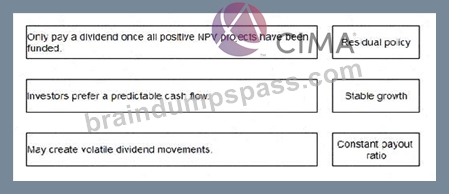
NEW QUESTION # 56
The directors of a multinational group have decided to sell off a loss-making subsidiary and are considering the following methods of divestment:
1. Trade sale to an external buyer
2. A management buyout (MBC)
The MDO team and the external buyer have both offered the same price to the parent company for the subsidiary.
Which of the following is an advantage to the parent company of opting for a MBO compared to a trade sale as the preferred method of divestment?
- A. Raise the cash more quickly.
- B. Focus on the core competencies of the business
- C. Avoid a hostile reaction from key management.
- D. Retain the know edge of key management.
Answer: C
NEW QUESTION # 57
A company's current earnings before interest and taxation are $5 million.
These are expected to remain constant for the forseeable future.
The company has 10 million shares in issue which currently trade at $3.60.
It also has a $10 million long term floating rate loan.
The current interest rate on this loan is 5%.
The company pays tax at 20%.
The company expects interest rates to increase next year to 6% and it's Price/Earnings (P/E) ratio to move to
9.5 times by the end of next year.
What percentage reduction in the share price will occur by the end of next year if the interest rate increase and the P/E movement both occur?
- A. Reduction of 1%
- B. Reduction of 0%
- C. Reduction of 7%
- D. Reduction of 5%
Answer: C
Explanation:
Let's walk it through carefully.
1. Current earnings and EPS
EBIT = 5m
Current interest (5% × 10m) = 0.5m
Profit before tax = 5.0 # 0.5 = 4.5m
Tax (20%) = 0.9m
Earnings = 4.5 # 0.9 = 3.6m
Shares = 10m # EPS# = 3.6 / 10 = 0.36
Current share price = 3.60 # current P/E = 3.60 / 0.36 = 10 (matches the question context).
2. Earnings next year with higher interest
New interest rate = 6% # interest = 10m × 6% = 0.6m
Profit before tax = 5.0 # 0.6 = 4.4m
Tax (20%) = 0.88m
Earnings = 4.4 # 0.88 = 3.52m
EPS# = 3.52 / 10m = 0.352
3. New share price using new P/E
Expected P/E next year = 9.5
Price1=EPS1×P/E1=0.352×9.5=3.344\text{Price}_1 = \text{EPS}_1 \times \text{P/E}_1 = 0.352 \times 9.5 =
3.344Price1=EPS1×P/E1=0.352×9.5=3.344
4. Percentage reduction in share price
Current price = 3.60
New price # 3.344
Drop = 3.60 # 3.344 = 0.256
% reduction=0.2563.60#7.1%#7%\%\ \text{reduction} = \frac{0.256}{3.60} \approx 7.1\% \approx
7\%% reduction=3.600.256#7.1%#7%
So the closest option is A. Reduction of 7%.
NEW QUESTION # 58
A company is considering the issue of a convertible bond compared to a straight bond issue (non-convertible bond).
Director A is concerned that issuing a convertible bond will upset the shareholders for the following reasons:
* it will dilute their control
* the interest payments will be higher therefore reducing liquidity
* it will increase the gearing ratio therefore increasing financial risk Director B disagrees, and is preparing a board paper to promote the issue of the convertible bond rather than a non-convertible.
Advise the Director B which THREE of the following statements should be included in his board paper to promote the issue of the convertible bond?
- A. The convertible bond may not dilute control as the bond holder has an option to choose conversion.
- B. Issuing a convertible bond will have a more favourable impact on the gearing ratio than a non- convertible bond.
- C. The coupon rate on the convertible bond will be lower than that on a non-convertible bond.
- D. Over the life of the bond, a convertible will be more expensive than a non-convertible.
- E. When converted into shares, the company will receive a cash inflow which can be used for future investments.
Answer: A,B,C
Explanation:
A). May not dilute control - A convertible bond does not cause immediate dilution. Bondholders only become shareholders if they choose to convert, usually when the share price performs well. So dilution is potential and future, not automatic at issue.
B). Lower coupon - A core feature of convertibles is that investors accept a lower interest (coupon) rate than on an equivalent straight bond, because they are being compensated by the conversion option. This directly rebuts the concern that interest payments will be higher.
D). More favourable impact on gearing - Compared with issuing a straight bond, a convertible is often viewed as "quasi-equity". Under modern financial reporting, part of the convertible may be classified as equity, and if conversion happens later, the bond liability disappears and is replaced by shares, reducing gearing. So, from a strategic financing perspective, convertibles are typically seen as less damaging to gearing than an equivalent non-convertible bond.
Options C (no cash inflow on conversion) and E (more expensive over life) are incorrect.
NEW QUESTION # 59
Using the CAPM, the expected return for a company is 10%. The market return is 7% and the risk free rate is
1%.
What does the beta factor used in this calculation indicate about the risk of the company?
- A. It has greater risk than the average market risk.
- B. It has the same risk as the average market risk.
- C. It is not possible to tell from CAPM.
- D. It has lower risk than the average market risk.
Answer: A
NEW QUESTION # 60
......
Genuine CIMAPRA19-F03-1 Exam Dumps Free Demo Valid QA's: https://www.braindumpspass.com/CIMA/CIMAPRA19-F03-1-practice-exam-dumps.html
Printable & Easy to Use CIMA Strategic level CIMAPRA19-F03-1 Dumps 100% Same Q&A In Your Real Exam: https://drive.google.com/open?id=1hJOEKTsM3Xp7HXS-0k_ybYWtfUt79C5e